Will Syria’s Druze Become Israel’s Kurds? The Proxy Protection Trap in Post-Assad Syria
September 17, 2026
The Houthis’ Advance to Bab al-Mandab: Iranian Checkmate to Saudi Arabia?
September 29, 2026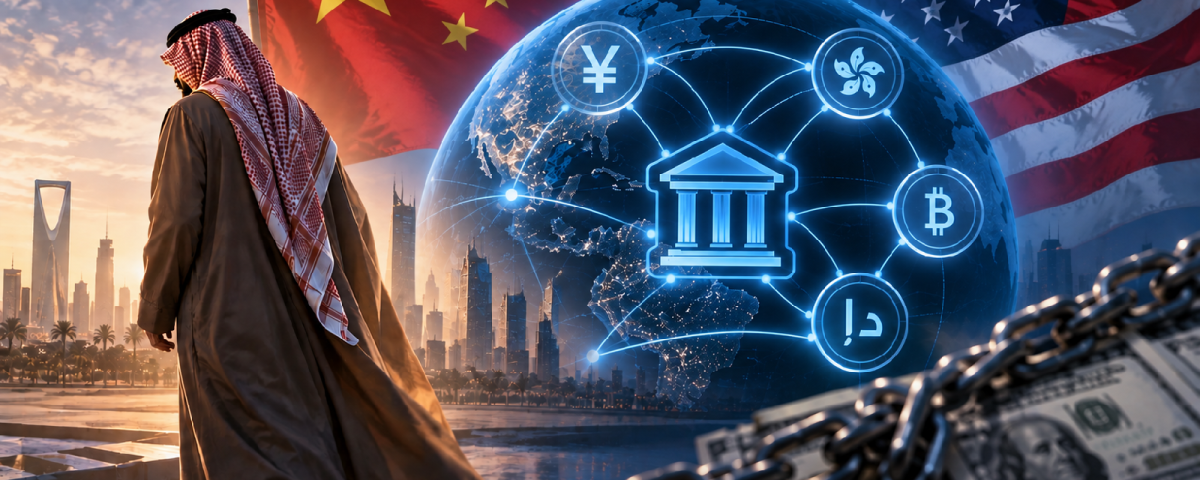
Saudi Arabia’s decision to leave the China-led mBridge digital payments project may look, at first glance, like a technical development in central-bank digital currencies. The more consequential question, however, is not why Riyadh left the platform, but why its withdrawal became public now, more than a year after Saudi Arabia had already completed its participation.
The timing is striking. The disclosure comes as Saudi Arabia faces renewed security pressures from Yemen and the Red Sea, while simultaneously deepening its economic relationship with China and maintaining its strategic dependence on the United States. It also comes as President Donald Trump prepares to host Chinese President Xi Jinping in Washington, placing the broader US-China competition over trade, technology, strategic commodities, and financial infrastructure back at the center of international politics.
Saudi Arabia joined mBridge as an observer in 2023 and became a full participant in 2024. It completed its proof-of-concept phase on May 13, 2025, after which its active participation ended. The Saudi Central Bank, SAMA, has described the withdrawal as part of the original plan rather than an abrupt policy reversal. Yet the political significance of the decision cannot be separated entirely from its timing.
More Than a Digital Currency Experiment
mBridge was designed as a cross-border payment platform using central bank digital currencies and distributed-ledger technology. Its central proposition is relatively straightforward: participating central banks can settle transactions more directly, reducing reliance on multiple intermediaries and potentially lowering the cost and time associated with international payments.
The project is not exclusively Chinese. It has involved the People’s Bank of China, Hong Kong, Thailand, the United Arab Emirates, Saudi Arabia and, at an earlier stage, the Bank for International Settlements. Nevertheless, China has played a central role in its development, giving mBridge significance well beyond financial technology.
The distinction from SWIFT is important. SWIFT primarily provides the messaging infrastructure through which financial institutions communicate payment instructions; it does not itself settle the underlying funds. mBridge, by contrast, is designed to facilitate the settlement layer through digital central-bank money. Its strategic significance therefore lies in the possibility of creating additional channels for international payments that are less dependent on conventional correspondent banking structures and dollar intermediation.
The project has already moved beyond a purely experimental concept. According to data cited by Reuters from the Atlantic Council, mBridge had processed more than 4,000 cross-border transactions worth approximately $55.5 billion by early 2026. The digital yuan accounted for roughly 95 percent of the settlement volume. Also, these figures do not mean that mBridge is replacing the global financial system, nor that the dollar is facing an imminent displacement. They demonstrate something more limited but strategically important: alternative payment infrastructure is becoming technically viable, and China is seeking a role in defining the standards through which future cross-border digital finance will operate.
The Contest Is About Infrastructure, Not Just Currency
China’s international financial strategy is often described as an attempt to internationalize the renminbi. That is part of the story, but the deeper competition concerns infrastructure. Beijing does not need the renminbi to replace the dollar globally in order to reduce dollar dependence. It can achieve incremental change by increasing the number of transactions that can be conducted directly in renminbi or other national currencies, without passing through the dollar as an intermediary.
That distinction matters. A transformation of the international monetary system does not necessarily begin with the collapse of an existing dominant currency. It can begin with the gradual creation of alternative payment channels, settlement mechanisms and financial standards.
This is why projects such as mBridge have attracted attention in Washington. US officials and financial experts have raised concerns about the possibility that China could gain greater influence over standards governing digital payments, including interoperability, privacy, security and the ability to enforce financial restrictions. At the same time, it would be an exaggeration to interpret every alternative payment initiative as an imminent threat to the dollar. The dollar continues to benefit from the depth of US financial markets, global liquidity, institutional credibility and its entrenched role in international trade and reserves. The more realistic question is therefore not whether the dollar will suddenly disappear, but whether the international financial system will gradually become more diversified.
Why Did Saudi Arabia Join—and Why Did It Leave?
Saudi participation in mBridge was consistent with a broader Saudi interest in financial technology and central-bank digital currencies. Riyadh and Abu Dhabi had previously tested the “Aber” project, which explored the use of a shared digital currency for financial settlement between the two countries.
Saudi Arabia’s departure from mBridge therefore should not be interpreted as a rejection of digital currencies or financial modernization. Rather, SAMA says it completed a specific proof-of-concept and subsequently ended its active participation. The Financial Times also reported that it would be inaccurate to conclude from the withdrawal alone that the decision resulted from direct US pressure.
That clarification is important. There is no publicly established evidence that Washington ordered Riyadh to leave mBridge. But separating the formal reason for the withdrawal from its wider geopolitical context is equally important. A technical decision made in 2025 can acquire a different political meaning when it becomes public in 2026.
Why Now?
The regional environment surrounding Saudi Arabia has changed sharply.
In September 2026, the Houthi conflict has intensified, with attacks threatening Saudi cities, energy infrastructure and maritime routes. Saudi Arabia confirmed that a Houthi ballistic missile had been launched toward Riyadh on September 19, although it was intercepted without reported casualties or significant damage.
The threat is not confined to Saudi territory. The Red Sea and Bab el-Mandeb are critical to global energy and commercial flows, particularly at a time when instability around the Strait of Hormuz has already disrupted maritime traffic.
This has placed Saudi Arabia in an increasingly complex strategic position. Riyadh continues to rely heavily on its security relationship with Washington, while simultaneously turning to Beijing for diplomatic and economic leverage. The most revealing example came only days before the mBridge disclosure. Reuters reported that Saudi Arabia had appealed to China for help in containing the Houthi escalation, prompting Beijing to privately ask Tehran to use its influence over the Houthis.
This episode illustrates the changing structure of Saudi strategic relations better than any single financial project. China is not merely an economic partner for Riyadh. In certain regional crises, Beijing is increasingly being treated as a diplomatic actor with access to Tehran that Washington does not possess. At the same time, the United States remains central to Saudi Arabia’s broader security architecture. The result is not a Saudi choice between China and America. It is a strategy of managing dependence on both.
A Signal to Washington—but Not a Break with Beijing
The timing of the mBridge disclosure may therefore carry a political message, even if the withdrawal itself was planned. Riyadh may want to make clear that cooperation with China does not automatically mean alignment with Beijing in the restructuring of the international financial system. At the same time, Saudi Arabia has little incentive to undermine a relationship with China that has become central to trade, energy, investment, infrastructure and technology.
This is consistent with the broader logic of Saudi foreign policy under Vision 2030: diversification of partnerships rather than replacing one external dependency with another. China has become one of Saudi Arabia’s most important economic partners, while Saudi Arabia remains an important energy supplier and investment destination for China. Chinese companies are increasingly involved in Saudi infrastructure, manufacturing, technology and major Vision 2030 projects.
For this reason, it would be misleading to interpret the mBridge withdrawal as a Saudi retreat from China. The more plausible interpretation is that Riyadh is drawing a distinction between economic partnership with China and strategic alignment with China’s vision of a less dollar-dependent financial order. That distinction gives Saudi Arabia greater room for maneuver.
The Gulf’s Larger Financial Question
Saudi Arabia’s decision also matters beyond the bilateral US-China relationship. The Gulf is becoming an important testing ground for digital finance, cross-border settlement and central-bank digital currencies. The UAE remains involved in mBridge, while Saudi Arabia has continued to explore digital financial infrastructure through other channels.
The broader question is whether Gulf economies will eventually develop more integrated regional payment mechanisms capable of settling a larger share of intra-regional and Asia-linked trade without relying exclusively on traditional financial intermediaries. That does not necessarily imply choosing between the dollar and the renminbi. A more plausible future may involve multiple settlement channels: dollars for some transactions, renminbi for others, local currencies where practical, and digital settlement platforms for selected cross-border payments.
Such diversification would fit the emerging structure of the global economy, in which economic power is becoming more distributed even while the dollar remains dominant.
Saudi Arabia’s Strategic Balancing Act
The significance of Saudi Arabia’s mBridge exit ultimately lies less in the project itself than in what it reveals about Riyadh’s broader strategic calculations. Saudi Arabia needs the United States for security and defense cooperation. It needs China for trade, energy, investment and technology. It also needs Europe, Asia and global capital markets to finance and implement Vision 2030. Its objective, therefore, is not to choose one power at the expense of the other, but to prevent either relationship from eliminating its strategic autonomy.
The disclosure of the mBridge withdrawal at this particular moment reinforces that balancing strategy. It may simply be the delayed public announcement of a technical decision completed in 2025. But its appearance amid the Yemen crisis, growing Red Sea insecurity, Saudi outreach to Beijing and renewed US-China engagement inevitably gives it a wider geopolitical meaning. Saudi Arabia is not abandoning China, nor is it turning away from the United States.
It is attempting something more difficult: to remain economically close to China, strategically connected to Washington, and sufficiently autonomous to avoid being absorbed into either side of an increasingly competitive global order. That may ultimately be the real significance of Riyadh’s departure from mBridge—not a shift from Washington to Beijing, but an effort to preserve Saudi freedom of action between them.
Prof. Shaher Al Shaher
Dr. Shaher Al SHAHER is an Associate Professor at the School of International Studies, Sun Yat-Sen University, China. Shaher@mail.sysu.edu.cn